 Your business in 360°
Currency effects in your results: how to account for them correctly
Changes in exchange rates must be recognised in the accounts: transactions are recorded at the rate on the transaction date, and balances at the end of the reporting period are remeasured at the rate on the last day. The resulting differences go to the result of financing and investing activities, and where their effect is material they must be disclosed in the explanatory notes.
In short:
- A realised difference arises when settlement takes place at a different rate from the one on the invoice date, while an unrealised difference comes from remeasuring unpaid amounts at the end of the period, so compare it with your cash flow.
- If the ECB or the Bank of Lithuania does not publish a rate for a particular currency, the accounting policy may specify another recognised market source, but the choice must be documented and applied consistently.
- The remeasurement difference on investments in controlled foreign entities may be recorded in a foreign currency translation reserve in equity rather than in the profit and loss statement, until the company disposes of the investment.
- Before closing the period, assign someone to update the rates, reconcile balances with the general ledger and compare the accounting result with actual cash flows.
Contents
- Legal and VAS basis: what the standards require
- Realised and unrealised exchange differences: the effect on profit
- Rate sources and accounting policy: the ECB, the Bank of Lithuania and market sources
- How exchange differences are presented in the financial statements
- Practical steps for the finance team: processes and controls
- Journal entry examples: realised and unrealised results
- Year-end checklist for accountants
- The author’s perspective: how management should view currency effects
- Automated reports from Rivilė and Finvalda for currency remeasurement
- FAQ
- Sources
Legal and VAS basis: what the standards require
In Lithuania, accounting for foreign currency transactions is based on the Business Accounting Standards (VAS, Lithuania’s national accounting standards), and at international level the same logic is mirrored by IAS 21. Both agree on the essentials: initial recognition uses the rate on the transaction date, while subsequent measurement depends on whether an item is monetary or non-monetary.
Under the standards, a foreign currency transaction is recorded in euros on initial recognition, using the rate in force on the day the risks and rewards associated with the goods or services are transferred. This means the accountant does not have to wait for the payment date to fix the value of the transaction.
In practice, the finance team should keep the following to hand:
- The provisions of the Law on Accounting concerning the currency in which the accounts are kept.
- The text of the specific VAS governing the use of the transaction-date rate.
- A reference to IAS 21, if the company reports under international standards or has a foreign parent company.
Realised and unrealised exchange differences: the effect on profit
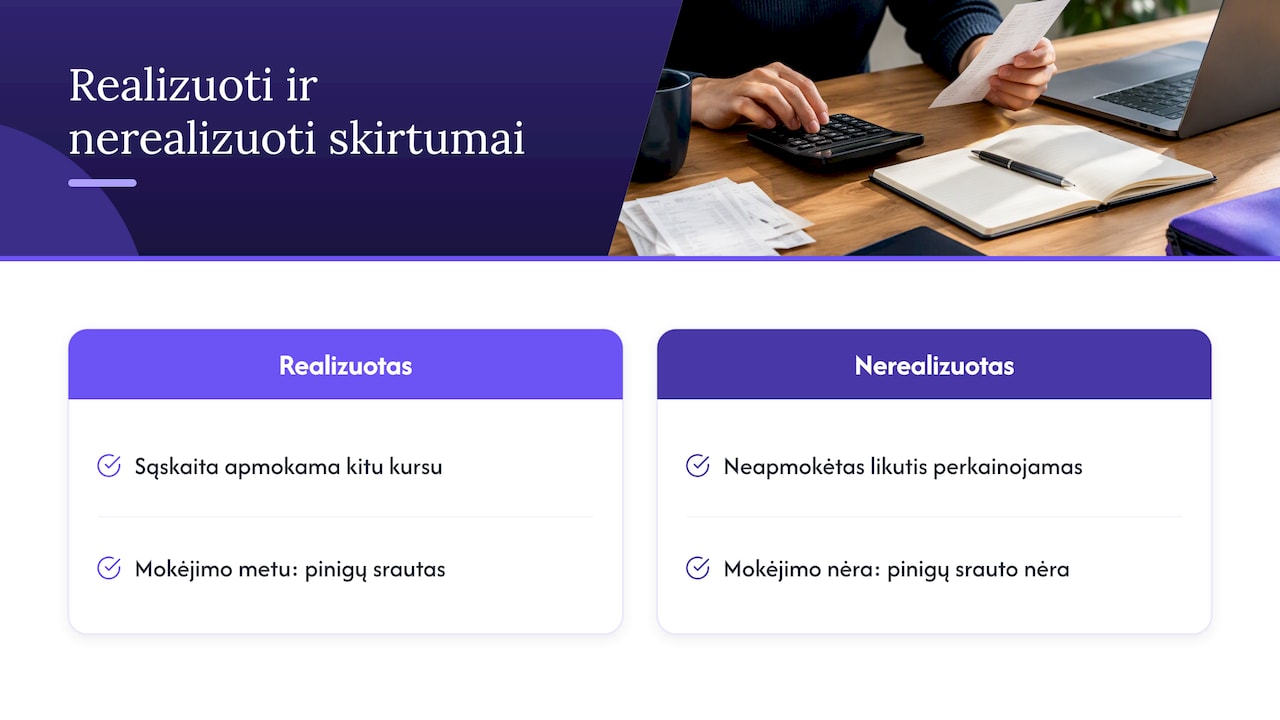
The distinction between realised and unrealised effects determines whether exchange rate movements merely change profit on paper or are already reflected in real cash flows. A realised difference arises when a transaction is actually completed, for example when a customer pays an invoice at a different exchange rate from the one on the invoice date.
Unrealised differences arise from remeasurement at the end of the reporting period: monetary assets and liabilities in foreign currency are retranslated at the rate in force on the last day of the period, even if no actual payment has taken place. It is this remeasurement that most often distorts the profit and loss statement, because it shows a profit or loss the company has not yet felt in cash.
Pro tip: Always review currency-driven changes in the profit line alongside the cash flow statement, or you risk misreading the company’s liquidity.
Rate sources and accounting policy: the ECB, the Bank of Lithuania and market sources
Standard practice is to rely on the official rates published by the European Central Bank or the Bank of Lithuania, as they are universally recognised and easy to verify. However, there are situations where there is simply no official rate for a particular currency or day.
In that case, the accounting policy may specify an alternative, generally recognised market source, such as a rate published by Bloomberg, Reuters or the Financial Times. What matters most is that the choice is consistent and documented, rather than changed every quarter for convenience.
What to set out in the accounting policy:
- Which source (the ECB, the Bank of Lithuania or a market data provider) is used for each currency.
- What happens when there is no official rate for a particular day.
- How often the choice of source is reviewed and who is responsible for it.
Where the choice of rate source has a material effect on the results, this should also be reflected in the explanatory notes, so that readers understand why that particular rate was applied.
How exchange differences are presented in the financial statements
Exchange differences are not a separate, isolated line: they are built into the standard structure of the financial statements, but in different ways depending on the nature of the situation.
- Ordinary differences on the translation of transactions and balances are recognised as income or expenses from financing and investing activities in the profit and loss statement, not in the result of operating activities.
- Where the currency effect relates to investments in controlled foreign entities, the translation difference may be recorded not in profit but as a foreign currency translation reserve in equity, until the investment is disposed of.
- If changes in exchange rates have a material effect on the results, the explanatory notes must disclose the nature of the transactions, the rates applied and their fluctuations.
In practice, this means the accountant must clearly separate which amounts belong to operating activities and which are purely the consequence of currency remeasurement; otherwise readers of the financial statements will get a distorted picture of the company’s underlying profitability.
Practical steps for the finance team: processes and controls
Sound accounting for exchange differences depends not only on the right formula but also on clearly allocated responsibilities within the team. Without a defined process, retranslations are often done at the last minute before reports are submitted, which increases the risk of errors.
Recommended structure:
- One person responsible for updating the rate source every month.
- Reconciliation of retranslated balances with the general ledger before the period is closed.
- Comparison of the remeasurement effect with actual cash flows, so that management can see the difference between the accounting result and the real one.
Linking remeasurements to cash flow analysis helps management quickly see whether a change in profit represents a real change in liquidity or merely an accounting fluctuation.
Pro tip: Before every quarterly close, draw up a separate list of foreign currency balances so that retranslation does not become a year-end emergency.
Journal entry examples: realised and unrealised results
Concrete examples make it quicker to apply the rules in your own accounting software.
- Realised difference: a customer pays an invoice in dollars some time after it was issued. You record the difference between the transaction-date rate and the payment-date rate as finance income or finance expense, depending on the sign.
- Unrealised difference: at year end you have an unpaid invoice in a foreign currency. You retranslate the balance at the rate on the last day and record the difference in a dedicated currency remeasurement account or directly in the profit and loss line, depending on the structure of the company’s chart of accounts.
In both cases, it is important that the line description clearly separates the currency effect from the result of core operating activities.
Year-end checklist for accountants
Before preparing the annual financial statements, it is worth working through a short but essential checklist.
- Retranslate all foreign currency cash, receivables and payables accounts at the rate on the last day of the reporting period.
- Check that the accounting policy clearly states the rate source used and that it has been applied consistently throughout the year.
- Assess whether the currency effect on the results is material and, if so, prepare the relevant paragraph in the explanatory notes.
- Compare the accounting foreign exchange gain or loss with actual cash flows, so that management has an accurate picture of liquidity.
The author’s perspective: how management should view currency effects
Management should assess the profit line together with cash flow. An accounting currency gain without the context of cash flow can create false confidence or needless anxiety. A clear disclosure policy and automated retranslation reduce the risk of manual errors and strengthen the confidence of creditors and investors.
— Analitika360
Automated reports from Rivilė and Finvalda for currency remeasurement
Retranslating foreign currency balances by hand every month takes up time an accountant could spend on analysis rather than moving data between files. Our Power BI solutions are designed for analysing Rivilė and Finvalda data, so that you can track income, expenses and the balance sheet.
Our reports help you analyse your business data. If you use Rivilė, you can start with the Rivilė Basic package at €59 a month, and for Finvalda users we offer Finvalda Basic at the same price. For more complex needs, such as multi-currency consolidation or a custom report structure, we offer bespoke projects at €70 an hour.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
When should an exchange difference be recognised in the accounts?
The transaction-date rate is applied when the transaction is recognised, and at the end of the reporting period monetary balances are retranslated at the rate on the last day. The resulting difference is recognised as income or expenses from financing and investing activities for that period.
What is the difference between realised and unrealised currency gains?
A realised gain or loss arises when a transaction is actually completed, for example when payment is made. An unrealised difference comes from year-end remeasurement and does not reflect an actual cash flow, so it is best assessed separately from liquidity.
Which exchange rate should be used if the ECB does not publish one?
Where the European Central Bank or the Bank of Lithuania does not publish a rate for a particular currency, the accounting policy may specify another generally recognised market source, such as Bloomberg or Reuters. The choice must be consistent and documented in the accounting policy.
When must the currency effect be disclosed in the explanatory notes?
Disclosure is mandatory where changes in exchange rates have a material effect on the company’s results. The explanatory notes set out the nature of the transactions, the rates applied and their fluctuations over the period.
Can the calculation of currency remeasurements be automated?
Power BI solutions using Rivilė or Finvalda data can help you analyse business data and prepare reports. This makes data analysis easier.
Sources
Below are the main sources this article draws on: the Business Accounting Standards, the provisions of the Law on Accounting and the international standard IAS 21 on the effects of changes in foreign exchange rates.
- E-seimas
- THE IMPACT OF RUSSIA’S WAR AGAINST UKRAINE ON THE MEASUREMENT OF ACCOUNTING DATA AND THE PRESENTATION OF INFORMATION IN FINANCIAL STATEMENTS UNDER VAS
- L 261/184 EN Official Journal of the European Union 13.10.2003